Conversation Practice | 3 things to never do with a credit card (video)
Você sabia que o recordista mundial de cartões de crédito acumulou mais de 1.400 deles, enquanto a maioria de nós tenta não cair nas armadilhas de apenas um? Os cartões foram desenhados para nos prender em juros e taxas, mas entender como funcionam a APR e os pagamentos mínimos é a chave para assumir o controle. Descubra as estratégias certas para fugir das dívidas e fazer o sistema finalmente trabalhar a seu favor!
| Audio | |
|---|---|
Normal | Slow |
| English Transcript | Tradução |
| 3 things to never do with a credit card | 3 coisas que você não deve fazer com um cartão de crédito |
| For over four decades, Walter Kavanaugh held a truly creditworthy record: the most credit cards held by one person. What began as a bet between friends led him to open over 1,400 cards, ranging from traditional bank-issued cards to those from airlines, gas stations, and even ice cream shops. | Por mais de quatro décadas, Walter Kavanaugh manteve um recorde verdadeiramente admirável: o maior número de cartões de crédito acumulado por uma única pessoa. O que começou como uma aposta entre amigos o levou a abrir mais de 1.400 cartões, variando de cartões bancários tradicionais a opções de companhias aéreas, postos de gasolina e até sorveterias. |
| Most people have far fewer credit cards. While useful for secure purchasing, handling emergencies, and building credit scores, credit cards can make it difficult to avoid overspending. Globally, the outstanding credit card debt exceeds trillions of dollars, and this is no accident. Credit card companies intentionally designed these systems to encourage spending and lock you into a cycle of interest and fees. | A maioria das pessoas tem muito menos cartões de crédito. Embora sejam úteis para compras seguras, emergências e para construir um bom histórico de crédito, os cartões de crédito podem dificultar a tarefa de evitar gastos excessivos. Em todo o mundo, a dívida pendente de cartão de crédito ultrapassa trilhões de dólares, e isso não é por acaso. As empresas de cartão de crédito projetaram esses sistemas intencionalmente para incentivar os gastos e prender você em um ciclo de juros e taxas. |
| So, how can you avoid their most common traps? It starts with card selection. | Então, como você pode evitar as armadilhas mais comuns? Tudo começa com a escolha do cartão. |
| Lenders often aggressively advertise perks like cashback, travel miles, and discounts, but these offers only seem generous. In reality, only a small portion of cardholders actually benefit: those who pay off their entire balance every month. According to one survey, 46% of American cardholders carry a revolving balance. For these users, the cost of interest and fees almost always exceeds the value of rewards. | Os credores costumam anunciar agressivamente vantagens como "cashback", milhas aéreas e descontos, mas essas ofertas apenas parecem generosas. Na realidade, apenas uma pequena parcela dos titulares de cartão realmente se beneficia: aqueles que pagam o valor total da fatura todos os meses. De acordo com uma pesquisa, 46% dos titulares de cartão americanos mantêm um saldo rotativo. Para esses usuários, o custo dos juros e das taxas quase sempre supera o valor das recompensas. |
| If you think you may fall into this category, financial experts recommend getting a card with the lowest Annual Percentage Rate (APR). This number is essentially the cost of borrowing money from the credit card company. You pay that cost through interest charges, which kick in as soon as you carry any balance past a statement due date. | Se você acha que pode se enquadrar nessa categoria, especialistas financeiros recomendam adquirir um cartão com a menor Taxa Anual Percentual (APR). Esse número é, essencialmente, o custo de pegar dinheiro emprestado com a empresa do cartão de crédito. Você paga esse custo por meio de cobranças de juros, que passam a valer assim que você carrega qualquer saldo além da data de vencimento da fatura. |
| While APRs are listed as yearly rates, for most cards, interest accrues daily. For example, a card with a 35% APR charges about 0.095% interest per day, so a revolving balance of $1,000 would accumulate approximately $29 in interest over a month. Meanwhile, a card with a lower APR, say 18%, would charge about $15 in interest during the same period. This difference can add up over time. If you were to make a $50 monthly payment towards that $1,000 balance, the card with the higher APR would take an extra $325 and an extra seven months to pay off. | Embora a APR seja informada em taxas anuais, para a maioria dos cartões, os juros acumulam diariamente. Por exemplo, um cartão com uma APR de 35% cobra cerca de 0,095% de juros por dia, portanto, um saldo rotativo de US$ 1.000 acumularia aproximadamente US$ 29 em juros ao longo de um mês. Enquanto isso, um cartão com uma APR mais baixa, digamos 18%, cobraria cerca de US$ 15 em juros durante o mesmo período. Essa diferença pode se acumular com o tempo. Se você fizesse um pagamento mensal de US$ 50 para esse saldo de US$ 1.000, o cartão com a APR mais alta levaria US$ 325 a mais e mais sete meses para ser quitado. |
| Interest fees can be even more complicated if you carry a balance and actively use a card; new purchases start accruing interest immediately, even if you pay off those purchases before the statement date. In other words, once you start to carry a balance, it is much more difficult to avoid interest charges going forward. Even after a bill is fully paid, you might still get one more charge—something called "residual interest"—for the days between your statement and payment date. | As taxas de juros podem ser ainda mais complicadas se você mantiver um saldo e usar o cartão ativamente; novas compras começam a acumular juros imediatamente, mesmo se você quitar essas compras antes da data da fatura. Em outras palavras, uma vez que você começa a manter um saldo rotativo, fica muito mais difícil evitar cobranças de juros no futuro. Mesmo depois que uma conta é totalmente paga, você ainda pode receber mais uma cobrança, algo chamado "juros residuais", referente aos dias entre o fechamento da sua fatura e a data do pagamento. |
| Low APR cards are the best option for minimizing these interest charges. However, be wary of cards that offer an exceptionally low APR for an introductory period. These flashy offers can mask things like complicated fee structures, steep late charges, and high default APRs that kick in once the introductory period ends. While many countries require companies to disclose these conditions, they are often buried in the fine print. | Cartões com baixa APR são a melhor opção para minimizar essas cobranças de juros. No entanto, tenha cuidado com cartões que oferecem uma APR excepcionalmente baixa por um período promocional. Essas ofertas chamativas podem mascarar coisas como estruturas de taxas complicadas, cobranças pesadas por atraso e taxas de APR padrão elevadas que passam a valer assim que o período promocional termina. Embora muitos países exijam que as empresas divulguem essas condições, elas geralmente ficam escondidas nas letras miúdas. |
| Payment structures can also be confusing. For example, many people mistake the minimum payment as the standard or even recommended amount to pay. In reality, it typically only covers interest fees and a small percentage of the balance. As a result, sticking to just the minimum payment can make even a low balance of $1,000 take over 18 years to pay off. | As estruturas de pagamento também podem ser confusas. Por exemplo, muitas pessoas confundem o pagamento mínimo com o valor padrão ou até mesmo recomendado a ser pago. Na realidade, ele normalmente cobre apenas as taxas de juros e uma pequena porcentagem do saldo. Como resultado, limitar-se apenas ao pagamento mínimo pode fazer com que até mesmo um saldo baixo de US$ 1.000 leve mais de 18 anos para ser quitado. |
| Paying the full card balance each month is the best way to avoid fees and actually benefit from rewards, but it is not always possible. So, what should you do if you find yourself in credit card debt? | Pagar o saldo total do cartão todos os meses é a melhor maneira de evitar taxas e realmente se beneficiar das recompensas, mas nem sempre isso é possível. Então, o que você deve fazer se se encontrar em dívidas de cartão de crédito? |
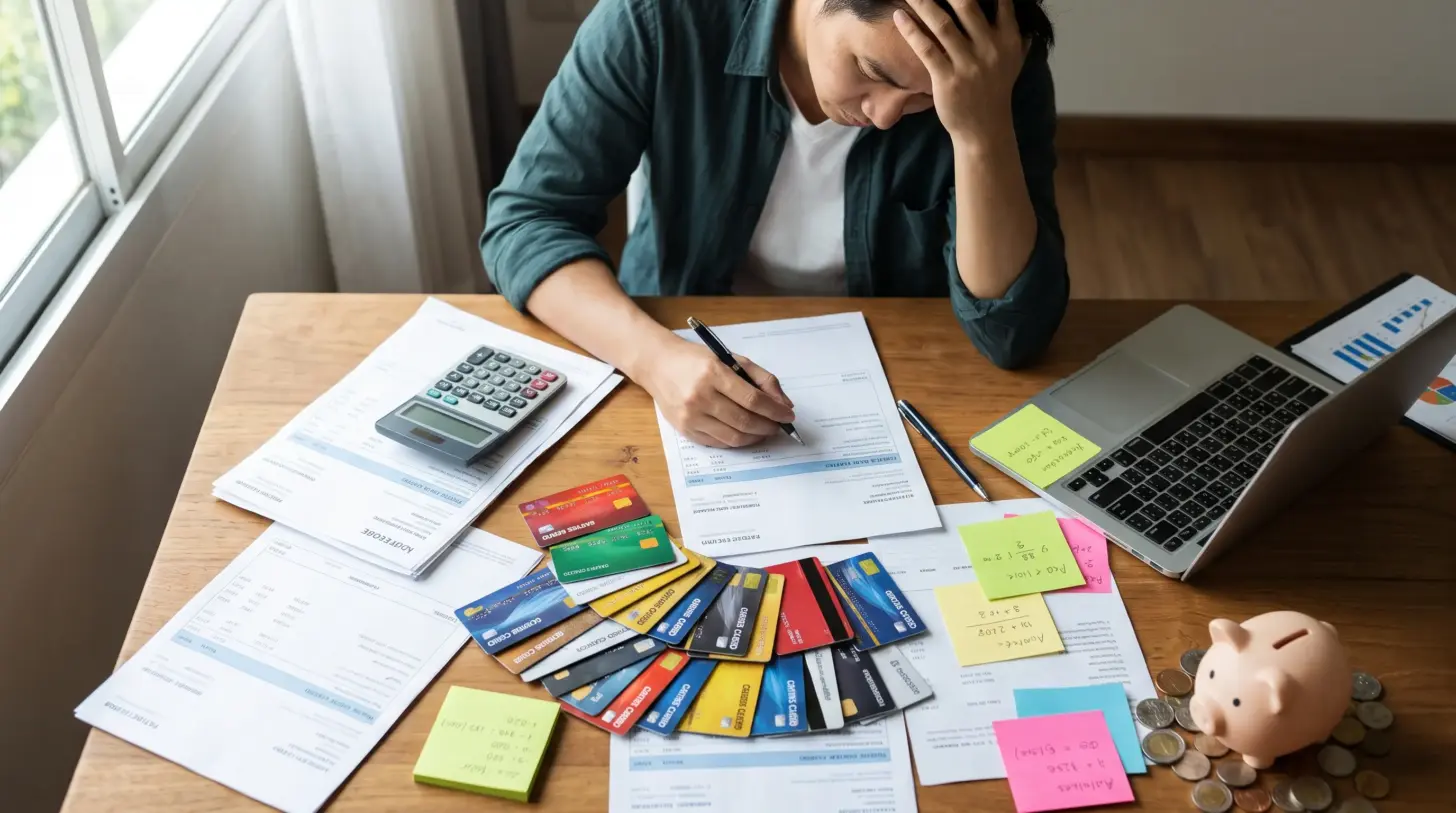
| The first step is to assess your finances and create a repayment plan. If the debt is on a high APR card, transferring your balance to a lower APR card may help; just be sure to check for balance transfer fees. If you are juggling debt on multiple cards, it may be tempting to pay off the lowest balance first. However, the most financially efficient strategy will always be to put any extra money towards the card with the highest APR, regardless of balance. The key is to chip away one card at a time—just don't be like Walter and open a thousand more in the meantime! | O primeiro passo é avaliar suas finanças e criar um plano de quitação. Se a dívida estiver em um cartão com APR alta, transferir seu saldo para um cartão com APR mais baixa pode ajudar; apenas certifique-se de verificar as taxas de transferência de saldo. Se você estiver lidando com dívidas em vários cartões, pode ser tentador pagar primeiro o saldo mais baixo. No entanto, a estratégia financeiramente mais eficiente sempre será direcionar qualquer dinheiro extra para o cartão com a APR mais alta, independentemente do saldo. O segredo é ir eliminando um cartão de cada vez, só não faça como o Walter e abra mais mil cartões nesse meio tempo! |
| TED has partnered with Gifted Savings to give $1,000 investment portfolios and free high-quality financial education to create a generation of financially capable young people. Want to bring Gifted Savings to a school or help fund a program in your community? Visit ed.ted.com/giftedsavings | O TED fez uma parceria com a Gifted Savings para doar carteiras de investimento de US$ 1.000 e educação financeira gratuita de alta qualidade para criar uma geração de jovens financeiramente capacitados. Quer levar a Gifted Savings para uma escola ou ajudar a financiar um programa em sua comunidade? Visite ed.ted.com/giftedsavings |
Contagem de palavras
A tabela abaixo exibe as palavras encontradas neste vídeo, bem como o número de vezes em que aparecem.
Veja também: Para que serve esta tabela?
| Freq. | Palavra | Freq. | Palavra | Freq. | Palavra |
|---|---|---|---|---|---|
| 30 | a | 29 | the | 25 | to |
| 16 | card | 16 | and | 14 | you |
| 14 | balance | 13 | of | 13 | interest |
| 11 | in | 10 | for | 9 | is |
| 9 | credit | 9 | cards | 9 | apr |
| 8 | with | 8 | $ | 7 | pay |
| 7 | if | 7 | can | 7 | be |
| 6 | these | 6 | it | 6 | fees |
| 6 | even | 6 | as | 5 | payment |
| 5 | over | 5 | off | 5 | most |
| 5 | charges | 4 | your | 4 | this |
| 4 | that | 4 | one | 4 | more |
| 4 | from | 4 | debt | 4 | carry |
| 4 | avoid | 4 | are | 4 | an |
| 3 | would | 3 | while | 3 | those |
| 3 | statement | 3 | so | 3 | period |
| 3 | people | 3 | only | 3 | month |
| 3 | may | 3 | make | 3 | low |
| 3 | like | 3 | high | 3 | extra |
| 3 | do | 3 | date | 3 | cost |
| 3 | always | 2 | what | 2 | walter |
| 2 | towards | 2 | things | 2 | their |
| 2 | ted | 2 | take | 2 | structures |
| 2 | start | 2 | small | 2 | savings |
| 2 | rewards | 2 | revolving | 2 | reality |
| 2 | purchases | 2 | percentage | 2 | or |
| 2 | open | 2 | once | 2 | on |
| 2 | often | 2 | offers | 2 | not |
| 2 | money | 2 | minimum | 2 | many |
| 2 | lowest | 2 | lower | 2 | kick |
| 2 | just | 2 | introductory | 2 | into |
| 2 | however | 2 | help | 2 | held |
| 2 | gifted | 2 | first | 2 | financially |
| 2 | financial | 2 | exceeds | 2 | example |
| 2 | difficult | 2 | create | 2 | complicated |
| 2 | companies | 2 | cardholders | 2 | but |
| 2 | between | 2 | best | 2 | benefit |
| 2 | aprs | 2 | any | 2 | actually |
| 2 | about | 1 | yourself | 1 | young |
| 1 | years | 1 | yearly | 1 | words |
| 1 | will | 1 | who | 1 | which |
| 1 | were | 1 | way | 1 | wary |
| 1 | want | 1 | visit | 1 | value |
| 1 | users | 1 | useful | 1 | use |
| 1 | up | 1 | typically | 1 | truly |
| 1 | trillions | 1 | travel | 1 | traps |
| 1 | transferring | 1 | transfer | 1 | traditional |
| 1 | timejust | 1 | time | 1 | through |
| 1 | thousand | 1 | think | 1 | they |
| 1 | tempting | 1 | systems | 1 | survey |
| 1 | sure | 1 | strategy | 1 | still |
| 1 | sticking | 1 | step | 1 | steep |
| 1 | stations | 1 | starts | 1 | standard |
| 1 | spending | 1 | soon | 1 | should |
| 1 | shops | 1 | seven | 1 | selection |
| 1 | seem | 1 | secure | 1 | scores |
| 1 | school | 1 | say | 1 | same |
| 1 | result | 1 | residual | 1 | require |
| 1 | repayment | 1 | regardless | 1 | record |
| 1 | recommended | 1 | recommend | 1 | rates |
| 1 | rate | 1 | ranging | 1 | quality |
| 1 | put | 1 | purchasing | 1 | program |
| 1 | 1 | possible | 1 | portion | |
| 1 | portfolios | 1 | plan | 1 | person |
| 1 | perks | 1 | per | 1 | paying |
| 1 | past | 1 | partnered | 1 | paid |
| 1 | overspending | 1 | outstanding | 1 | other |
| 1 | option | 1 | offer | 1 | number |
| 1 | no | 1 | new | 1 | never |
| 1 | multiple | 1 | much | 1 | months |
| 1 | monthly | 1 | mistake | 1 | minimizing |
| 1 | miles | 1 | might | 1 | meanwhile |
| 1 | meantime | 1 | mask | 1 | lock |
| 1 | listed | 1 | lenders | 1 | led |
| 1 | late | 1 | key | 1 | kavanaugh |
| 1 | juggling | 1 | issued | 1 | investment |
| 1 | intentionally | 1 | immediately | 1 | ice |
| 1 | how | 1 | him | 1 | highest |
| 1 | higher | 1 | have | 1 | has |
| 1 | handling | 1 | going | 1 | globally |
| 1 | give | 1 | giftedsavings | 1 | getting |
| 1 | get | 1 | generous | 1 | generation |
| 1 | gas | 1 | fund | 1 | fully |
| 1 | full | 1 | friends | 1 | free |
| 1 | four | 1 | forward | 1 | flashy |
| 1 | fine | 1 | find | 1 | finances |
| 1 | fewer | 1 | fee | 1 | far |
| 1 | fall | 1 | experts | 1 | exceptionally |
| 1 | every | 1 | essentially | 1 | entire |
| 1 | ends | 1 | encourage | 1 | emergencies |
| 1 | efficient | 1 | education | 1 | ed |
| 1 | each | 1 | during | 1 | due |
| 1 | dollars | 1 | discounts | 1 | disclose |
| 1 | difference | 1 | designed | 1 | default |
| 1 | decades | 1 | days | 1 | day |
| 1 | daily | 1 | cycle | 1 | creditworthy |
| 1 | cream | 1 | covers | 1 | countries |
| 1 | confusing | 1 | conditions | 1 | company |
| 1 | community | 1 | common | 1 | com |
| 1 | chip | 1 | check | 1 | chargesomething |
| 1 | charge | 1 | category | 1 | cashback |
| 1 | capable | 1 | called | 1 | by |
| 1 | buried | 1 | building | 1 | bring |
| 1 | borrowing | 1 | bill | 1 | bet |
| 1 | began | 1 | before | 1 | bank |
| 1 | away | 1 | at | 1 | assess |
| 1 | approximately | 1 | annual | 1 | amount |
| 1 | american | 1 | also | 1 | almost |
| 1 | airlines | 1 | aggressively | 1 | after |
| 1 | advertise | 1 | add | 1 | actively |
| 1 | accumulate | 1 | accruing | 1 | accrues |
| 1 | according | 1 | accident |